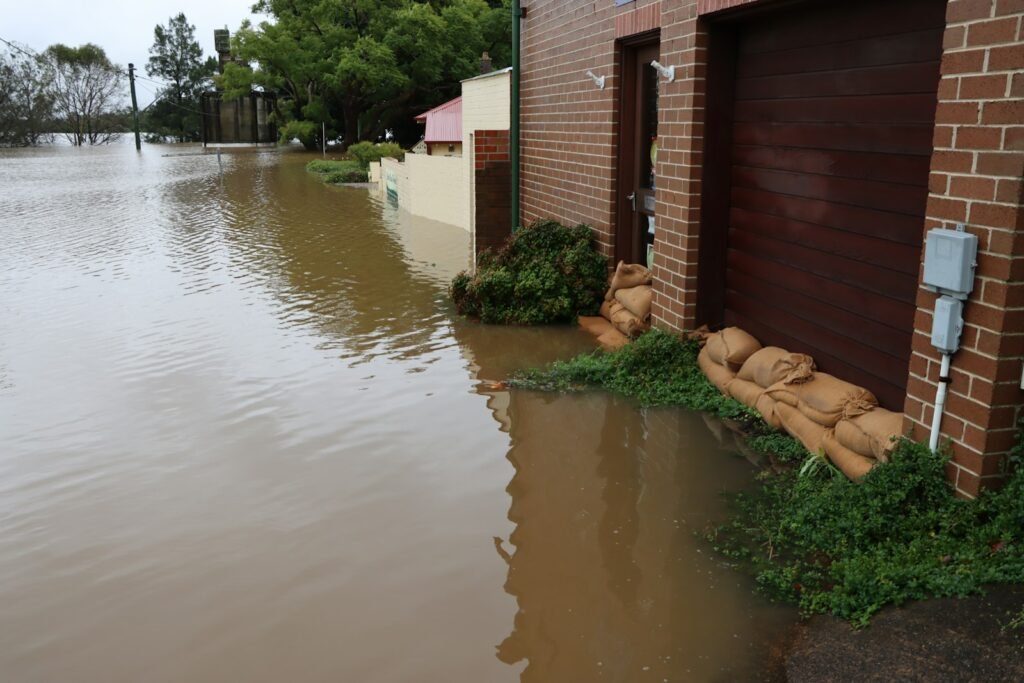
To find a flood zone in Palm Beach County, enter the address in the county’s free “Find Your Flood Zone” lookup or in FEMA’s Flood Map Service Center. If the home is in a high-risk zone, such as A, AE or VE, and you are using a federally backed mortgage, flood insurance is required. Outside those zones it is optional, but often worth buying.
Flood risk changed for many Palm Beach County homes when new FEMA flood maps took effect on December 20, 2024. Insurance rules have also changed, including a Citizens Property Insurance requirement that is phasing in for nearly every Citizens policy with wind coverage by 2027. This guide walks buyers through what to check, when to check it, and how to keep a flood question from derailing a closing.
Key takeaways
- New FEMA flood maps took effect in Palm Beach County on December 20, 2024, and moved thousands of eastern-county properties into high-risk zones.
- Zones that start with A or V are high risk. Lenders require flood insurance there for federally backed loans.
- NFIP policies cover up to $250,000 for the building and $100,000 for contents, and the usual 30-day wait does not apply when the policy is bought with a new mortgage.
- Citizens customers need flood coverage in high-risk zones now, and every Citizens policy with wind coverage will need it starting January 1, 2027.
- Check the flood zone, the seller’s flood disclosure and a flood quote during your inspection period, not after it.
How do you find your flood zone in Palm Beach County?
Finding your flood zone in Palm Beach County takes a few minutes with an address. Use the county’s “Find Your Flood Zone” lookup tool or FEMA’s Flood Map Service Center at msc.fema.gov. Both show the official FEMA zone and map panel for the property. For homes inside a city, the city’s floodplain office can confirm the result.
A few tips that make the lookup more useful:
- Look at the whole lot, not just the pin. A zone line can cross a property. Lenders look at where the building sits.
- Note the base flood elevation. In AE and VE zones the map shows a base flood elevation (BFE), the height floodwater is expected to reach in a 1% annual chance flood. This number matters for insurance pricing.
- Ask the right office. Palm Beach County handles unincorporated areas. Its flood zone line is 561-233-5374, or email floodzone@pbc.gov. Residents of Jupiter, West Palm Beach, Wellington and other cities should contact their city’s floodplain office.
Use our home search to find a property, then run its address through the county tool before you book a showing. It is a quick way to know what to ask about.
What changed with the December 2024 flood maps?
The new FEMA flood maps for Palm Beach County took effect on December 20, 2024. According to Palm Beach County, thousands of residents in the eastern part of the county were added to high-risk flood zones, and more than 16,000 parcels saw their base flood elevation rise by one foot or more.
Local news coverage quoting FEMA put the change at about 5,000 properties moving into high-risk zones and about 900 moving out. Either way, the result is the same for buyers: a listing description, an old survey or a seller’s memory of the zone may be out of date.
What this means in practice:
- A home that never needed flood insurance may need it now if it has a mortgage and moved into a high-risk zone.
- A higher base flood elevation can mean higher flood premiums, and it can affect future renovation rules for the building.
- The seller’s insurance history may not match your quote. Their premium may reflect an older map or an older rating method.
What do the FEMA flood zone letters mean?
FEMA flood zone letters describe a property’s flood risk. Zones beginning with A, including A, AE, AH and AO, are high risk, with about a 1% chance of flooding in any year. Zones beginning with V, such as VE, are coastal high-risk areas facing waves. Zones B, C and X are moderate to low risk.
| Zone | Risk level | Flood insurance with a federally backed mortgage | Where you see it |
|---|---|---|---|
| VE, V | Coastal high risk, with wave action | Required | Oceanfront and some inlet properties |
| AE, A | High risk (1% annual chance flood) | Required | Low areas near the Intracoastal, lakes and canals |
| AH, AO | High risk, shallow flooding or ponding | Required | Low spots where water collects |
| X, B, C | Moderate to low risk | Not required, but the lender may still ask for it | Most inland neighborhoods |
High-risk A and V zones together are called the Special Flood Hazard Area. “Moderate to low risk” does not mean no risk. Heavy rain, storm surge and drainage problems can flood homes outside high-risk zones, which is why many owners buy a policy anyway.
When is flood insurance required in Palm Beach County?
Flood insurance is required in Palm Beach County when a home is in a high-risk flood zone, such as A, AE or VE, and is financed with a mortgage from a federally regulated or federally insured lender. That covers most mortgages, including conventional, FHA and VA loans. Citizens Property Insurance also has its own flood requirement for its policyholders.
If you pay cash, no lender can require flood insurance. That does not make the risk go away. A cash buyer in a high-risk zone is taking on the full cost of any flood damage, and federal disaster help is not a substitute for insurance.
A lender can also require flood insurance outside a high-risk zone. Some do for certain properties, so ask your loan officer early.
Buying in a coastal town? Shakir can pull the flood zone and the seller’s flood disclosure for any home you are considering before you make an offer.
What does NFIP flood insurance cover?
NFIP flood insurance, sold through the National Flood Insurance Program run by FEMA, covers up to $250,000 for the building and up to $100,000 for contents on a home. Coverage is bought through an insurance agent. A new policy usually has a 30-day waiting period, but there is no wait when it is bought with a new mortgage.
The waiting period rules are important for buyers:
- Standard rule: a new NFIP policy takes effect 30 days after purchase.
- Loan exception: there is no waiting period when the policy is required in connection with making, increasing, extending or renewing a mortgage. A policy bought for your closing can start at closing.
- Map change exception: a one-day wait applies in a newly mapped high-risk zone when the policy is bought within 12 months of the map change. For the December 20, 2024 Palm Beach County maps, that window has closed.
If the home is worth more than the NFIP limits, ask your agent about private flood insurance or excess flood coverage. Some private policies offer higher limits or different terms. Compare the deductible, what counts as covered property, and whether the lender will accept the policy.
How is flood insurance priced under Risk Rating 2.0?
Risk Rating 2.0 is the method FEMA uses to price NFIP flood insurance. It applied to new policies starting October 1, 2021, and to renewals starting April 1, 2022. Instead of relying mainly on the flood zone, it looks at each home’s own flood risk. For most policyholders, yearly increases are capped at 18%.
Under the older system, two homes in the same zone often paid similar rates. Under Risk Rating 2.0, two neighbors can pay different premiums because the method weighs features specific to each building, such as how close it is to water and what it would cost to rebuild.
Two things for buyers to know:
- The seller’s premium may be lower than yours. A long-time owner may still be stepping up toward a full-risk rate under the 18% cap. Get your own quote.
- Ask whether the policy can be assigned. In some cases a seller’s NFIP policy can be transferred to the buyer. Your insurance agent can tell you whether that helps in your case.
Does Citizens Property Insurance require flood insurance?
Yes. Under Florida law, Citizens Property Insurance requires flood coverage for homes in high-risk flood zones at any value. Outside high-risk zones, the requirement is phasing in by dwelling coverage amount: $600,000 or more from 2024, $500,000 or more from 2025, $400,000 or more from 2026, and every policy starting January 1, 2027.
| Start date | Citizens policies that must carry flood insurance (outside high-risk zones) |
|---|---|
| January 1, 2024 | Dwelling coverage of $600,000 or more |
| January 1, 2025 | Dwelling coverage of $500,000 or more |
| January 1, 2026 | Dwelling coverage of $400,000 or more |
| January 1, 2027 | All Citizens policies |
Homes in high-risk zones already need flood coverage with Citizens regardless of value. Condo unit-owner policies and policies that exclude wind coverage are exempt. The flood limits must be equal to or greater than the dwelling and contents limits on the Citizens policy, or the NFIP maximum if those limits are not available.
If your home insurance quote comes from Citizens, add a flood quote to your budget even for a home in zone X. From 2027 it will be required for every Citizens homeowner with wind coverage. Home insurance quotes also depend on inspections, which we cover in our guide to 4-point and wind mitigation inspections.
What is an elevation certificate and how do you find one?
An elevation certificate is a document, prepared by a surveyor, engineer or architect, that shows how high a building sits compared with the expected flood level for its zone. It does not set your premium on its own, but it can help an agent find discounts. In Palm Beach County, many are online in the My GeoNav map.
How to look for one:
- Ask the seller. Owners often have one from a past purchase, permit or insurance policy.
- Check My GeoNav. Palm Beach County’s My GeoNav map has an “Elevation Certificate” layer that shows certificates on file.
- Ask the floodplain manager. The county or city floodplain office may have one for the address.
- Order a new one. If none exists, a surveyor can prepare it. Ask about timing so it is ready before your inspection period ends.
How do community flood discounts work in Palm Beach County?
Community flood discounts come from FEMA’s Community Rating System (CRS), which rewards cities and counties for flood protection work with lower NFIP premiums for residents. As of April 2024, unincorporated Palm Beach County and several towns earned Class 5, a 25% discount in high-risk zones. Palm Beach Gardens was Class 10, with no discount.
| Community (as of April 2024) | CRS class | NFIP discount |
|---|---|---|
| Unincorporated Palm Beach County | Class 5 | 25% |
| Jupiter | Class 5 | 25% |
| Juno Beach | Class 5 | 25% |
| North Palm Beach | Class 5 | 25% |
| West Palm Beach | Class 5 | 25% |
| Wellington | Class 5 | 25% |
| Boynton Beach | Class 5 | 25% |
| Delray Beach and the Town of Palm Beach | Class 6 | 20% |
| Boca Raton | Class 7 | 15% |
| Palm Beach Gardens | Class 10 | 0% |
CRS classes can change from year to year. Ask your insurance agent which discount applies to the address you are buying. You can read more about individual towns in our guides to Jupiter, Juno Beach and Palm Beach Gardens.
What must a Florida seller disclose about flooding?
Florida sellers must give buyers a written flood disclosure under section 689.302 of the Florida Statutes, at or before the time the sales contract is signed. Since October 1, 2025, it covers known flood damage during the seller’s ownership, any flood insurance claims, and any flood repair assistance the seller received from any source, not only from federal programs.
The law first took effect on October 1, 2024, and was expanded in 2025. The disclosure is a starting point, not the full picture:
- It covers what the seller knows during their ownership, not the home’s full history.
- “No claims” does not mean “no flooding.” An owner may have had damage and paid for repairs without filing a claim, which the disclosure also asks about.
- Read it next to the flood zone, the elevation certificate and your inspection report.
Sellers can learn more about their disclosure duties in our guide to selling a home in Palm Beach County.
How does hurricane season affect buying insurance?
Hurricane season in the Atlantic runs from June 1 to November 30. When a tropical storm or hurricane watch or warning is issued for Florida, insurers can stop writing new policies until the threat passes. This is called a binding suspension. Citizens, for example, began a statewide binding suspension on September 27, 2025.
During a binding suspension, you may not be able to buy a new policy or raise your coverage. If your closing falls during that window and your insurance is not yet bound, the closing can be delayed.
How to protect your closing date:
- Get home and flood insurance quotes in the first days of your inspection period.
- Bind coverage as soon as your lender and agent are ready, rather than waiting for the week of closing.
- Watch the forecast in late summer and early fall, when storms are most common, and build a little extra time into the contract.
A buyer’s flood checklist, step by step
A buyer’s flood checklist in Palm Beach County has three stages: before the offer, during the inspection period, and before closing. The goal is to know the zone, flood history and insurance cost while you can still renegotiate or cancel. On the standard Florida “As Is” contract, the inspection period is 15 days unless the parties agree otherwise.
| Stage | What to do |
|---|---|
| Before the offer | Look up the flood zone, check My GeoNav for an elevation certificate, and ask for the seller’s flood disclosure |
| Inspection period, first days | Order inspections and request home and flood insurance quotes |
| Inspection period, before it ends | Review the quotes with your lender, confirm the total monthly payment, and decide whether to proceed |
| Before closing | Bind the flood policy so it starts at closing, and send proof to your lender and the closing agent |
Flood insurance is one of several costs to plan for. See our guide to closing costs in Palm Beach County for the rest. If you are looking at a condo, the association’s coverage matters too, which we cover in our guide to buying a condo in Palm Beach County.
Shakir is a REALTOR, not an insurance agent. Always get flood and home insurance advice and quotes from a licensed insurance agent.
Ready to look at homes? Search current listings across north and central Palm Beach County and save the ones you like.
Frequently asked questions
How do I check if a house is in a flood zone in Palm Beach County?
Enter the address in Palm Beach County’s free “Find Your Flood Zone” lookup tool or in FEMA’s Flood Map Service Center at msc.fema.gov. Both show the official zone from the flood maps that took effect December 20, 2024. For homes inside a city, the city’s floodplain office can confirm the zone and may have an elevation certificate.
Do I need flood insurance if I am in zone X?
Usually not for a federally backed mortgage, because zone X is moderate to low risk. Your lender can still require it, and Citizens Property Insurance customers will need flood coverage on every policy with wind coverage from January 1, 2027. Many owners in zone X buy flood insurance anyway, because flooding also happens outside high-risk zones.
Is there a waiting period for flood insurance when buying a home?
Not when the policy is bought in connection with a new mortgage. NFIP policies normally take effect after 30 days, but the wait is waived when the policy is required for making, increasing, extending or renewing a loan. That means a flood policy bought for your purchase can start on the day you close.
How much flood coverage can I get from the NFIP?
The National Flood Insurance Program covers up to $250,000 for the building and up to $100,000 for contents on a home. If the home would cost more than that to rebuild, ask an insurance agent about private flood insurance or excess flood coverage, and confirm that your lender will accept the policy you choose.
Can a seller hide past flooding in Florida?
Florida law requires sellers to disclose known flood damage during their ownership, flood insurance claims, and flood repair assistance from any source, at or before the signing of the contract. Buyers should still check the flood zone, look for an elevation certificate and use their inspection period, because the disclosure only covers what the seller knows.
Sources
- Palm Beach County: Find Your Flood Zone lookup
- Palm Beach County: Update on flood zones
- FEMA Flood Map Service Center
- FloodSmart: What is my flood zone?
- FloodSmart: Buy a policy (limits and waiting periods)
- FloodSmart: Elevation certificates
- FEMA: Risk Rating 2.0 frequently asked questions (PDF)
- Citizens Property Insurance: Updates to the flood coverage law
- Citizens Property Insurance: Binding suspension notice, September 27, 2025
- Florida Statutes, section 689.302: Flood disclosure in the sale of real property
- Florida Realtors: Florida expands flood disclosures
- Palm Beach County: My GeoNav elevation certificates quick reference (PDF)
- Palm Beach County: Community Rating System
- NOAA: 2026 Atlantic hurricane season outlook
- Citizens Property Insurance: flood insurance requirement
This article is general information, not legal, tax or insurance advice. Rules, rates and deadlines change, so confirm the details with the official source, a Florida real estate attorney, your title company, your insurance agent or a tax professional before you rely on them.
With over 10 years of experience as a successful real estate agent, I have proudly helped hundreds of happy buyers and sellers achieve their real estate goals. I’m passionate about helping clients find their dream homes, sell their properties with confidence, and navigate every step of the process with ease. My commitment to personalized service, strong relationships, and exceptional results makes every real estate journey a rewarding experience.
REALTOR® with Continental Properties, Inc. in North Palm Beach. Florida license #3346934.